SUBSCRIBE
Enter your Name and Email address to get
the newsletter delivered to your inbox.
Please include name of person that directed you to my online newsletter so I can thank them personally.
Craig Lundquist, MBA, ChFC®, CRPC®
VP of Wealth Management
651-773-2757
Kristin Becker
Senior Administrative Assistant
651-773-2821
Ideal Wealth Advisors
Located at Ideal Credit Union
8499 Tamarack Road
Woodbury, MN 55125
CRPC conferred by College for Financial Planning
Your home is your castle, and it's important to protect its value and comfort. Many people unknowingly underinsure their property because they don't fully understand their homeowner's insurance coverage. The transition between the end of the year and the new year is an ideal time to review your insurance needs with a trusted professional. Here's essential information to consider before doing so.
Expensive jewelry, collections such as art, cars, and antiques, and costly hobby equipment (for cars, woodworking, and other crafts) generally require additional coverage. To insure these items for full value, you should have jewelry and collections professionally appraised and keep purchase receipts for all items. A personal property endorsement or floater to supplement your homeowners' insurance is needed for adequate protection. Rates vary among insurers.
If you operate a home office or run a small business from home, you'll need insurance that fills coverage gaps in your standard policy. For professionals who maintain a secondary home office—contractors, attorneys, accountants, real estate agents, writers/editors, and bookkeepers—consider adding a permitted incidental occupancies rider to your homeowner's policy. If you have a primary home office, you'll need to upgrade to a home business endorsement. This endorsement covers various home-based business activities while falling short of a more costly full business policy.
1164451
Enter your Name and Email address to get
the newsletter delivered to your inbox.
Please include name of person that directed you to my online newsletter so I can thank them personally.
Enter your Name, Email Address and a short message. We'll respond to you as soon as possible.
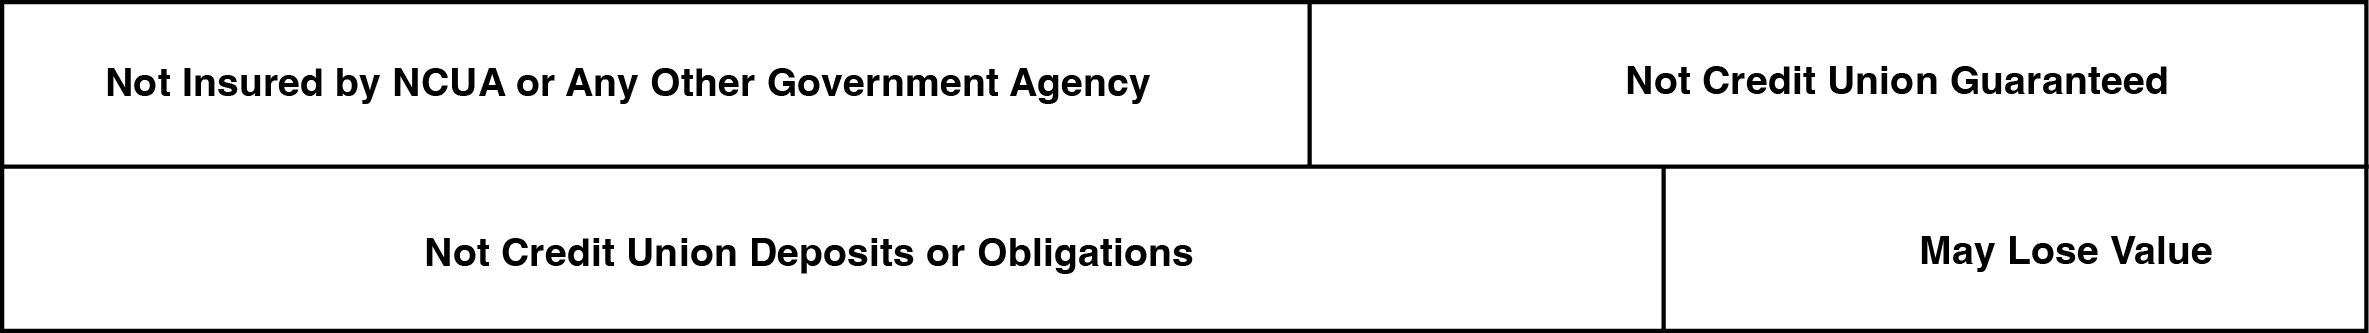
Securities and advisory services are offered through LPL Financial (LPL), a registered investment advisor and broker-dealer (member FINRA/SIPC). Insurance products are offered through LPL or its licensed affiliates. Ideal Credit Union and Ideal Wealth Advisors are not registered as a broker/dealer or investment advisor. Registered representatives of LPL offer products and services using Ideal Wealth Advisors, and may also be employees of Ideal Credit Union. These products and services are being offered through LPL or its affiliates, which are separate entities from and not affiliates of Ideal Credit Union or Ideal Wealth Advisors. Securities and insurance offered through LPL or its affiliates are:
The information and opinions contained in this web site are obtained from sources believed to be reliable, but their accuracy cannot be guaranteed. The publishers assume no responsibility for errors and omissions or for any damages resulting from the use of the published information. This web site is published with the understanding that it does not render legal, accounting, financial, or other professional advice. Whole or partial reproduction of this web site is forbidden without the written permission of the publisher.