SUBSCRIBE
Enter your Name and Email address to get
the newsletter delivered to your inbox.
Please include name of person that directed you to my online newsletter so I can thank them personally.
Craig Lundquist, MBA, ChFC®, CRPC®
VP of Wealth Management
651-773-2757
Kristin Becker
Senior Administrative Assistant
651-773-2821
Ideal Wealth Advisors
Located at Ideal Credit Union
8499 Tamarack Road
Woodbury, MN 55125
CRPC conferred by College for Financial Planning
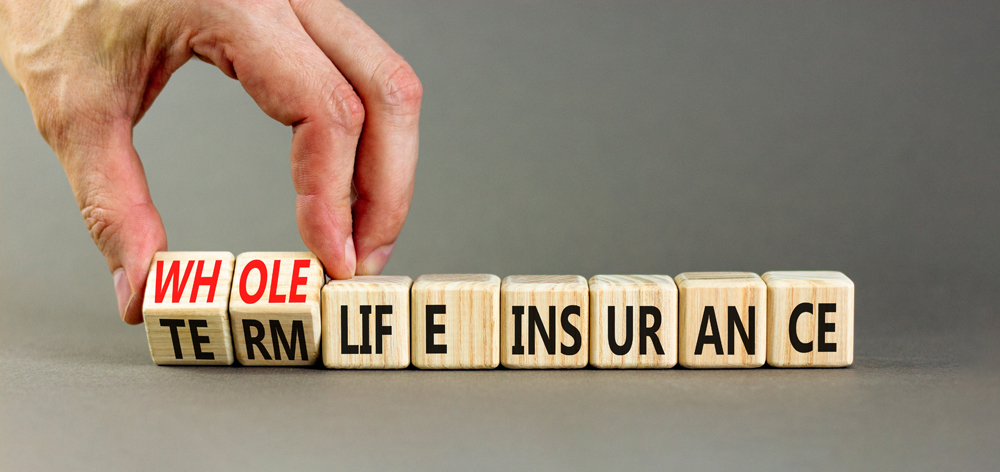
Will the Federal Reserve lower the federal funds rate this month? Probably not at the top of your mind—but it matters if you're deciding whether to buy whole life insurance.
Understanding how federal interest rates affect whole life insurance can help you make better policy decisions. Whole life insurance provides a death benefit and accumulates cash value, funded by a portion of your premiums. This cash value grows at a guaranteed minimum rate, though that rate and any additional returns are influenced by changes in the federal funds rate, affecting how much your cash value earns over time.
A fixed-premium policy lets you lock in that lower premium for life, while still delivering the same portfolio-hedging and retirement planning benefits that a whole life policy offers in any economy.
But remember, whole life insurance isn't primarily about cash value growth. Its guaranteed death benefit provides peace of mind regardless of market fluctuations. If you're treating the policy mainly as a savings vehicle, interest rates matter more; if your priority is providing for loved ones, fluctuating rates are less critical.
1164451
Enter your Name and Email address to get
the newsletter delivered to your inbox.
Please include name of person that directed you to my online newsletter so I can thank them personally.
Enter your Name, Email Address and a short message. We'll respond to you as soon as possible.
Securities and advisory services are offered through LPL Financial (LPL), a registered investment advisor and broker-dealer (member FINRA/SIPC). Insurance products are offered through LPL or its licensed affiliates. Ideal Credit Union and Ideal Wealth Advisors are not registered as a broker/dealer or investment advisor. Registered representatives of LPL offer products and services using Ideal Wealth Advisors, and may also be employees of Ideal Credit Union. These products and services are being offered through LPL or its affiliates, which are separate entities from and not affiliates of Ideal Credit Union or Ideal Wealth Advisors. Securities and insurance offered through LPL or its affiliates are:
The information and opinions contained in this web site are obtained from sources believed to be reliable, but their accuracy cannot be guaranteed. The publishers assume no responsibility for errors and omissions or for any damages resulting from the use of the published information. This web site is published with the understanding that it does not render legal, accounting, financial, or other professional advice. Whole or partial reproduction of this web site is forbidden without the written permission of the publisher.