CONTACT US
Enter your Name, Email Address and a short message. We'll respond to you as soon as possible.
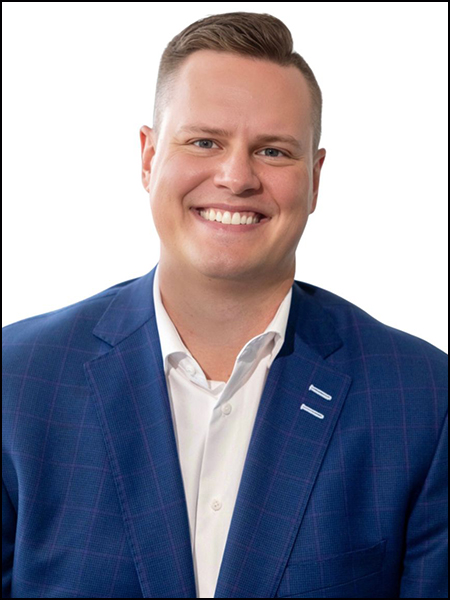
Doug Oosterhart, CFP®
Owner/Financial Advisor
LifePoint Planning, PLLC
1821 Walden Office Square, Suite 400
Schaumburg, IL 60173
Phone: 844-505-3618
Email: doug@lifepointplanning.com
Website: www.lifepointplanning.com
For many years, financial professionals have recommended that most people delay taking Social Security benefits until age 70. The reason is compelling: Each year you delay beyond your full retirement age increases your monthly benefit by 8% in most cases. For those with a full retirement age of 67, waiting until age 70 boosts your monthly check by 24%.
Second, benefits include built-in inflation protection through annual cost-of-living adjustments (COLAs). By delaying, you receive these increases on a higher base, protecting your purchasing power over decades.
Third, the 8% delayed retirement credit significantly outperforms current interest rates on safe investments. It's a guaranteed return that's hard to match elsewhere — and unlike market investments, it carries no risk of loss.
Deciding when to claim Social Security is one of the most important and irreversible retirement decisions you'll make. The choice will affect your income for the rest of your life. Before deciding, consult your financial advisor and tax professional to ensure the strategy aligns with your overall retirement plan, health, and financial needs.
Source: https://www.ssa.gov/benefits/retirement/planner/delayret.html
Enter your Name, Email Address and a short message. We'll respond to you as soon as possible.
LifePoint Planning, PLLC and LTM Marketing Solutions, LLC are unrelated companies. This publication was prepared for the publication’s provider by LTM Marketing Solutions, LLC, an unrelated third party. Articles are not written or produced by the named representative.
The information and opinions contained in this web site are obtained from sources believed to be reliable, but their accuracy cannot be guaranteed. The publishers assume no responsibility for errors and omissions or for any damages resulting from the use of the published information. This web site is published with the understanding that it does not render legal, accounting, financial, or other professional advice. Whole or partial reproduction of this web site is forbidden without the written permission of the publisher.